

PayPal - Pay, Send, Save
by PayPal Mobile
4.2
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.2
- Price
- Free
- Download
- 100.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
PayPal - Pay, Send, Save is the kind of finance app that can feel useful almost immediately because it brings several familiar money tasks into one place. I can use it to send money, receive it, pay for purchases, and manage certain payment choices without switching between several separate services. That convenience is its strongest first impression, but the more important question is whether it still deserves a regular place on my phone after the initial novelty disappears.
My answer is mostly yes, especially for people who already pay online, regularly send money to other people, or want one recognizable account for shopping and transfers. It is less compelling if I only need a basic bank transfer tool or if I prefer keeping every financial activity inside my bank’s own app. The experience is not perfect, and finance apps deserve a more careful standard than ordinary shopping or social apps, but PayPal remains a practical all-rounder with a clear everyday purpose.
From quick setup to a useful first week
The first-week appeal comes from how easy it is to understand the main jobs the app is built around. The developer is PayPal Mobile, and the app belongs to the finance category rather than trying to be a general-purpose shopping platform. Its central actions are straightforward: send money, receive money, pay for something, and review activity connected with the account.
I appreciate that this makes the app approachable for someone who does not want to learn a complicated financial dashboard. A person can open it with a specific task in mind instead of wondering where to begin. If a friend needs to be paid back, the relevant path is obvious. If I want to check whether a recent purchase went through, the account activity gives me a more useful starting point than searching through email receipts alone.
The app is free to install and has an Everyone content rating, which makes it broadly accessible from a store perspective. Its current version is 8.107.0, and it supports devices running Android 7.0 or later. Those details matter most when deciding whether an older phone can handle it, although the quality of the experience will also depend on the device, operating system condition, and connection.
During an initial week, the most convincing use case is a small cluster of ordinary tasks rather than one dramatic feature. I might use it to pay a seller online, send a share of a meal to a friend, then return later to check the transaction history. That sequence shows why a dedicated payment account can feel more convenient than handling each action through separate bank screens or payment pages.
A realistic example is splitting a household purchase. One person pays at checkout, another sends their share later, and both people want a record that is easier to identify than a vague bank transfer description. PayPal can be useful here because the payment conversation and the transaction are connected to a recognizable service. I still need to check the recipient carefully before confirming anything, but the workflow is less awkward than passing around account details for every small reimbursement.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
One practical habit I recommend from the beginning is treating the activity screen as a record to review, not just a list to ignore. I would look at the recipient, amount, and status after important payments, particularly when a transfer is time-sensitive. That small check can prevent confusion later, because a payment that is pending, completed, or reversed should not be treated as interchangeable.
The app also makes sense for online shoppers who encounter PayPal at checkout. Instead of repeatedly entering payment information into unfamiliar merchant pages, I can use an account that I already recognize. That does not remove the need to judge whether a seller is trustworthy, and it does not turn every purchase into a risk-free transaction, but it can make the payment step feel more controlled and familiar.
Where the first week can become less smooth is when the user expects every money movement to behave exactly like a bank transfer. PayPal is a payment service, not a replacement for every function of a traditional bank. The balance, payment flow, and transfer timing may not match the habits built around a bank account. Anyone moving money for an urgent bill should check the status and destination instead of assuming that pressing send means the funds are immediately available to the other person.
The app’s store presence reflects substantial adoption: it has passed one hundred million installs and holds a 4.2 average from about 3.7 million ratings, alongside roughly 439 thousand written reviews. Those figures suggest that it is not a niche tool, but popularity should not replace personal testing. A service can be widely used and still be a poor fit for someone who wants only local banking features or who dislikes payment accounts outside their main bank.
What becomes useful after the first impression
After the first few transactions, I find the app more valuable as a habit than as a one-time utility. The habit is simple: open it before sending, confirm the details, complete the action, and later use the activity record to reconcile what happened. That routine is more important than any feeling of speed because financial mistakes usually come from rushing through familiar screens.
A less obvious strength is the separation between paying and reviewing. Many people think of payment apps only as buttons for sending money, but the history can become a lightweight personal reference. I can use it to identify recurring purchases, remember who has already been reimbursed, and spot activity that does not fit my expectations. It is not a full budgeting system, so I would not rely on it alone for monthly planning, but it can fill gaps in my financial memory.
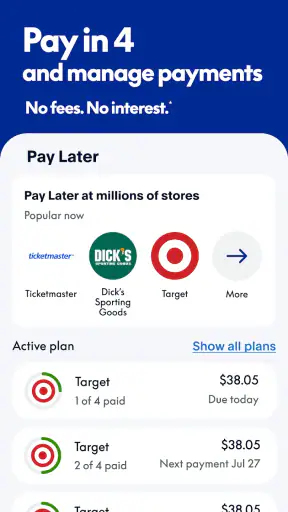
The “pay in 4” option mentioned in the store summary may appeal to shoppers who prefer dividing an eligible purchase into installments. I would treat that as a budgeting decision, not as a discount. Splitting a payment can make a purchase easier to fit into a short-term plan, but it can also make the total cost feel less visible. Before choosing it, I would consider whether the purchase is necessary, whether the schedule fits my income, and whether another payment method would be clearer.
This is one area where the app can become either more useful or more tiring depending on the user’s discipline. If I use installment-style payment only after checking the full commitment, it can be a deliberate tool. If I select it simply because the first payment looks smaller, the convenience works against me. The app presents the option, but the responsibility for deciding whether it belongs in my routine remains mine.
For people who receive money from several contacts, the app can also reduce the need to remember which conversation belongs to which transfer. That is valuable for informal arrangements such as shared meals, group gifts, or household expenses. I would still keep a separate note for larger or recurring obligations, because a payment history is not automatically the same thing as a complete financial ledger.
Compared with a conventional bank app, PayPal is often more comfortable for online checkout and person-to-person payments where both sides already use the service. A bank app may be the better choice for direct account management, scheduled banking tasks, and a complete view of money held in one institution. Compared with a single-purpose wallet, PayPal can feel broader because sending, receiving, shopping, and installment payment sit under the same account, but that breadth also means there are more screens and decisions to understand.
Compared with handing over card details on every website, the app can reduce repeated entry and give me a familiar payment checkpoint. However, I would not describe it as universally better. Some merchants may provide a smoother direct-card experience, and users who value absolute simplicity may prefer one payment method rather than another account layer. The right choice depends on whether the convenience of a central payment identity outweighs the extra account management.
Keeping it useful without letting it become tiring
I find the best way to keep a payment app from becoming another source of noise is to give it a clear job: handle the transactions it makes easier, then review them at a time that suits me. In this section, I’ll focus on a light-touch routine for staying aware without checking every screen out of habit, before looking at how readable navigation affects that routine.
The real maintenance burden
PayPal does not demand the same kind of daily maintenance as a budgeting app, but financial accounts should not be left completely unattended. I would review recent activity after meaningful transactions, keep contact details current, and avoid treating old payment habits as proof that every future request is safe. The maintenance is modest, yet skipping it can make small problems harder to understand.
One of my preferred workflows is to use the app for the transaction and a separate personal system for the monthly overview. After sending money, I can mark the expense in my budget or note, then use PayPal’s history later to verify the amount. This avoids expecting one app to provide perfect budgeting, banking, and payment management at the same time.
Another useful habit is separating convenience from urgency. If someone asks for money quickly, I would pause and verify the recipient through a second channel before confirming. A familiar interface can make a transaction feel trustworthy even when the request itself deserves scrutiny. The app can make sending easy; it cannot decide whether the person asking is genuine or whether the payment is appropriate.
I would also avoid using a payment balance as if it were automatically the same as money in my primary bank account. Before relying on funds for a deadline, I would check where the money is and what the transaction status says. That extra step is especially important for users who move between receiving, spending, and transferring money rather than leaving funds in one place.
For families or shared households, the maintenance question becomes more complicated. A single person may handle most payments, but other people still need a clear understanding of what was sent and why. I find the app more useful when each transaction has a recognizable purpose and when larger shared expenses are recorded somewhere outside the payment history. Otherwise, the account can become a long stream of amounts that are technically accurate but difficult to interpret months later.
Where fatigue starts to appear
The main source of fatigue is that financial convenience can create more choices. Sending money, receiving money, shopping, and considering installment payments are not identical activities, even when they appear in one app. A user who only wants to pay a friend may feel that the broader service is more than necessary. The app earns its space when I use several of its functions, not when I open it once every few months for one isolated task.
There is also a psychological burden in having another financial account to watch. Even if the app saves time at checkout, I still need to remember that transactions, balances, and payment decisions deserve attention. People who already have several wallets, bank apps, and shopping accounts may find that PayPal simplifies one part of their routine while adding another place to check.
Installment payments are a particular fatigue point for anyone who dislikes fragmented commitments. A purchase divided into several payments can be easy to forget, especially when the original item no longer feels new. I would use this feature sparingly and keep the full obligation visible in my budget. If I cannot explain how the future payments fit into my month, I would choose a simpler payment method.
Another limitation is that the best experience depends on the other person or merchant being comfortable with the service. If a friend uses a different payment method or a seller does not offer PayPal, the app cannot create compatibility by itself. In those situations, a bank transfer, card, or another wallet may be more practical. This is not a defect unique to PayPal, but it affects whether the app becomes a genuine habit.
I would also skip it as my main tool if I need a detailed financial control center. Someone looking for deep spending categories, comprehensive account aggregation, or a full banking relationship may be better served by a bank app or dedicated budgeting software. PayPal is strongest at moving money and supporting payments; it is not automatically the best place to build an entire financial system.
Security also requires personal effort. I would use a strong, unique password, protect access to the phone, and inspect transaction details before approving anything. I would not share login codes or approve a payment merely because a message appears urgent. These are sensible precautions for any finance app, but PayPal’s familiar name can make users lower their guard, which is exactly when careful checking matters most.
Who will keep opening it month after month?
The strongest long-term users are people who repeatedly shop online, send money to friends or family, or receive payments through the same account. For them, the app’s value is cumulative: each familiar transaction reinforces the reason to keep it installed. The service becomes part of a routine rather than an app opened only because a store happened to display its name at checkout.
It is also a good fit for someone who wants a recognizable middle layer between personal payment details and online merchants. I would still review every checkout and avoid assuming that a payment intermediary settles every dispute or problem automatically, but the central account can make online purchasing feel less scattered.
On the other hand, I would not recommend making it a permanent fixture solely because it is popular. If my bank already handles transfers, mobile payments, and purchase records in a way I understand, adding PayPal may create duplication. The app should earn its place through repeated convenience, not through the assumption that every finance tool is useful simply because it has a large user base.
My long-term verdict
After the first-week appeal fades, PayPal - Pay, Send, Save still has a credible reason to remain installed. Its lasting value comes from combining person-to-person payments, receiving money, online shopping, and the option to pay in 4 within one familiar finance app. I find that combination more useful than a single-purpose wallet when my payment life is spread across friends, merchants, and occasional installment decisions.
Its weaknesses are mostly about boundaries and habits. It does not replace a complete bank account for every purpose, it can feel unnecessary when my existing bank already covers my needs, and its payment flexibility can encourage choices that require careful budgeting. The app is convenient, but convenience should shorten a sensible process, not remove the checking that protects me from mistakes.
For a friend, I would recommend it when they have a clear recurring use: frequent online purchases, regular reimbursements, or a need to receive money through a widely recognized service. I would suggest keeping a separate budget and verifying important transactions rather than relying on the app as the sole record of financial life. That approach lets the convenience remain useful without allowing it to become invisible background spending.
Overall, I see it as a durable practical tool rather than a novelty. The free price and broad device support make trying it easy, while the 4.2 average from millions of ratings shows that many users find enough value to keep using it. My final judgment is positive but selective: it earns lasting space when it replaces repeated payment friction, not when it merely adds another account to manage.
Pros
- Widely accepted for online payments.
- Simple and intuitive user interface.
- Secure transactions with encryption.
- Fast setup and easy account linking.
- Supports multiple currencies.
Cons
- Transaction fees can be high.
- Customer support can be slow.
- Limited buyer protection for some items.
- Account holds may occur unexpectedly.
- Currency conversion rates aren't favorable.
FAQs for PayPal - Pay, Send, Save
What is PayPal and how does it work?
PayPal is a digital payment platform that allows users to send and receive money online securely. It connects to your bank account, credit, or debit card, enabling transactions without sharing financial details. Whether you're shopping online, sending money to friends, or receiving payments for services, PayPal simplifies the process with just a few clicks.
Is it safe to use PayPal for transactions?
Yes, PayPal is known for its high-security standards. It uses end-to-end encryption to protect your data, and transactions are monitored 24/7 for fraud prevention. Additionally, PayPal offers a Purchase Protection program for eligible purchases, ensuring your money is safe if something goes wrong with your transaction.
Are there any fees associated with using PayPal?
Creating a PayPal account and making purchases are generally free. However, fees may apply for certain transactions, such as sending money internationally or withdrawing funds to a bank account. Business transactions and currency conversions might also incur charges, so it's important to review PayPal’s fee structure based on your usage.
Can I use PayPal without linking a bank account or credit card?
While you can create a PayPal account without linking a bank account or credit card, your usage will be limited. To fully utilize PayPal’s features, such as making purchases or sending money, you’ll need to link a payment method. This linkage also helps verify your account, enhancing security and transaction limits.
What should I do if I encounter issues with PayPal?
If you encounter any issues, PayPal offers several support options. You can access the Help Center for troubleshooting guides, contact customer service via phone or email, or engage with the PayPal Community for advice. It's also advisable to report any suspicious activity immediately for prompt resolution.
Read About PayPal - Pay, Send, Save in Your Language

PayPal - Pay, Send, Save
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via app-feedback@paypal.com, visit https://www.paypal.com/mobile, or review their https://www.paypal.com/webapps/mpp/ua/privacy-full.










